Originally published 17 September 2026. This educational article reflects its publication date; check current rules and suitability before taking action.
A regular bank credit is not the same as a guaranteed investment return. This distinction matters when a family moves from earning a salary to drawing money from accumulated savings. A systematic withdrawal plan can organise payments from a mutual fund, but the payment schedule does not remove investment risk.
For retirees, people approaching retirement and adult children helping parents in Chennai and across India, the useful question is not simply “Which SWP pays the most?” It is how withdrawals, market movements, expenses and the remaining portfolio work together. This guide explains the mechanics and the questions to discuss before starting.
Quick answer: An SWP generally redeems mutual-fund units at scheduled intervals to provide a chosen withdrawal. The payment may include your invested capital. A sustainable retirement plan considers spending needs, other income, liquidity, risk, taxes and the possibility of poor returns early in retirement.
1. Understand what an SWP actually does
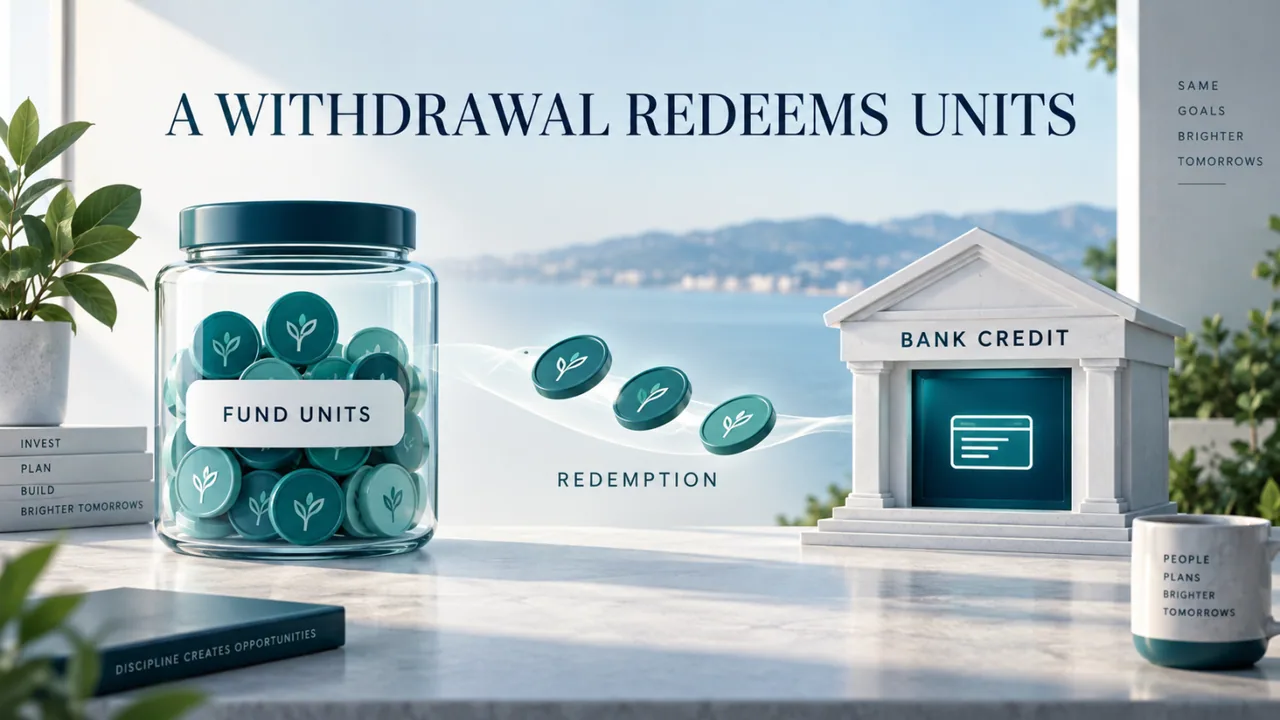
SWP stands for systematic withdrawal plan. It is a transaction facility offered under the relevant scheme's terms, not a separate asset class and not a promise of a fixed return. The fund investment continues to have the risks of its underlying portfolio.
HDFC Mutual Fund's withdrawal documentation explains that withdrawals by redemption reduce the investor's unit balance. This is the central mechanism to understand: money reaches the bank because units are redeemed, not because the fund necessarily earned that exact amount during the month.
Check the actual scheme documents for permitted frequency, minimum amounts, registration requirements, settlement arrangements and restrictions. Facilities and terms differ. Do not choose a fund solely because its withdrawal form appears convenient.
2. Separate spending needs from the withdrawal setting
Start with household spending. List essential monthly costs, irregular annual bills, healthcare expenses, family commitments and discretionary items. Identify which costs are reasonably predictable and which could change sharply.
Then list income available independently of the proposed SWP, such as a pension or other dependable receipts. The gap is what the portfolio may need to support. A household with a pension covering essential expenses has a different planning problem from one relying entirely on investments.
Do not overlook annual costs simply because the proposed withdrawal is monthly. Insurance renewal, repairs and travel can make the bank balance look comfortable for several months before a large bill arrives. A cash-flow calendar helps reveal that pattern.
3. See how the number of units changes
Consider a simplified hypothetical withdrawal of ₹10,000. If the applicable net asset value, or NAV, is ₹20 per unit, the redemption requires 500 units before considering any relevant charges or taxes. At an NAV of ₹16, the same ₹10,000 requires 625 units.
The cash amount is unchanged, but more units leave the portfolio at the lower price. That is why a smooth bank-credit pattern can hide an uneven investment experience. The example illustrates arithmetic only; it is not a projection for any scheme.
Review both the withdrawals received and the remaining investment value. Looking only at the bank statement can create a false impression that the investment is behaving like a guaranteed monthly-income product.
4. Do not confuse withdrawal rate with return
A withdrawal rate expresses withdrawals relative to a chosen portfolio value. An investment return describes the change generated by the investment over a period. They are different measures, and one does not guarantee the other.
For example, withdrawing ₹3 lakh over a year from an initial ₹50 lakh is a 6% withdrawal relative to that starting amount. It does not mean the portfolio earned 6%. The value could rise or fall while the withdrawals continue.
Be cautious with illustrations that show a constant return every year and a growing balance indefinitely. Such calculations can explain assumptions, but actual market returns do not arrive in an even sequence. Ask what happens under less favourable conditions.
5. Understand the risk of poor early returns
When withdrawals occur during a market decline, the investor can redeem a larger number of units to meet the same cash requirement. Those units are no longer present to participate if the market later recovers. The order of returns can therefore matter, not only their average.
This is often called sequence-of-returns risk. Picture two journeys with different road conditions near the beginning. A retirement plan that must pay bills every month cannot simply ignore the early stretch and focus only on the eventual destination.
Planning responses can include a suitable liquidity reserve, diversified assets and flexibility in non-essential spending. The right arrangement depends on the family's resources and risk capacity. No single cash-buffer formula eliminates every risk.
6. Build a liquidity plan before choosing a payout
Money needed for near-term commitments should be accessible through an arrangement appropriate to those commitments. Consider bank access, transaction timing, emergency needs and who can assist if the account holder is unwell.
Do not place the entire household reserve into a market-linked investment simply because an SWP can send regular payments. Liquidity means being able to meet a need when it arises, on acceptable terms. It is not just the existence of an online redemption button.
Discuss how the spending account will be replenished and what happens if a payment date falls around a holiday or an operational delay. These details are mundane, but they matter when the money pays for essential expenses.
Illustrative case study: a retirement plan with an overlooked annual bill
Imagine a fictional retired couple whose routine expenses are ₹45,000 a month. A pension covers ₹30,000, so they initially think the portfolio needs to provide only ₹15,000 monthly. During a detailed review, they identify ₹1.2 lakh of annual insurance, maintenance and other planned costs that were missing from the monthly calculation.
Spread across a year, those bills add the equivalent of ₹10,000 a month. The planning gap is therefore larger than the first estimate. This does not automatically mean they should set a ₹25,000 SWP; the available corpus, risks, reserves and alternative choices must also be assessed.
The lesson is to define the need before selecting the mechanism. These figures are hypothetical and do not describe a Bright Vision client, recommended allocation or expected investment outcome.
7. Allow for changing expenses
Retirement spending does not remain fixed forever. Prices change, healthcare needs evolve and family responsibilities can shift. A withdrawal that feels adequate today may lose purchasing power over time.
Use several assumptions when discussing the plan. What if routine expenses rise faster than expected? What if a major repair occurs? What if one income source stops? These questions help identify where the plan has flexibility and where it is fragile.
Increasing the withdrawal each year can address spending pressure, but it also changes the demand on the portfolio. An automatic annual increase is not evidence that the investment can support it. Review the full picture before changing the instruction.
8. Check taxes, exit loads and scheme restrictions
A withdrawal by redemption can have tax consequences. The relevant treatment depends on the investment, holding period, transaction and current law. The amount credited to the bank should not be assumed to equal taxable profit, and a tax estimate should not be guessed from the SWP label.
Ask a qualified tax professional to review the actual holdings and planned redemptions. Also check exit loads, lock-ins and any restrictions in the scheme documents. Units purchased on different dates can require careful attention.
Keep statements and transaction records. A clear record helps with tax preparation and performance review. This article deliberately avoids a universal tax-rate table because the correct answer depends on the investment and applicable rules.
9. Review the portfolio without chasing last year's winner
The investment mix should reflect the household's needs and capacity to absorb losses. A fund with a strong recent return is not automatically appropriate for funding retirement expenses. Consider the underlying assets, concentration, volatility, liquidity and costs.
Ask how the proposed portfolio behaves when markets fall and how withdrawals will be managed. A useful discussion explains trade-offs instead of promising a high payout with no erosion. Capital can decline, and a plan may need adjustments.
Where professional services are used, understand the provider's role, applicable authorisation, fees or commissions and scope of advice. Product distribution, investment advice and tax advice are not interchangeable descriptions.
10. Decide your review triggers in advance
Set a routine review date and identify events that should trigger an earlier conversation: a major health expense, loss of other income, a substantial portfolio change or a new family obligation. This reduces the chance of making decisions only when anxiety is high.
A review should compare actual spending, withdrawals, remaining value and future commitments. It should also revisit the original assumptions. If the plan is under pressure, discuss options such as reducing discretionary withdrawals, changing timing or reviewing the investment mix with appropriate professional help.
Do not assume that continuing the original payout is always the disciplined choice. A retirement plan is useful because it can respond to changed circumstances.
Questions to ask before starting an SWP
- Which expenses must the portfolio cover, and which income sources already exist?
- How much accessible reserve will remain outside the withdrawal arrangement?
- What risks are present in the underlying scheme?
- How will poor early returns affect the remaining corpus?
- What taxes, loads, lock-ins and operational terms apply?
- What would cause us to reduce or revise withdrawals?
- Who will review the plan, and how is that service paid for?
Frequently asked questions
Is an SWP a guaranteed pension?
No. It is generally a scheduled redemption facility. The underlying investment remains subject to its risks and terms.
Can an SWP use up my capital?
Yes. Withdrawals can include invested capital, and the corpus can decline or be exhausted depending on returns and withdrawals.
Is one withdrawal percentage safe for everyone?
No. Retirement duration, spending, other income, portfolio risk and flexibility differ between households.
Can the withdrawal amount be changed?
Check the particular scheme's procedures and notice requirements. Changes should also be assessed against the household's wider financial plan.
Plan the income before setting the instruction
An SWP can make transactions convenient. A retirement plan makes the purpose and trade-offs clear. For a retirement cash-flow discussion, contact Bright Vision Investment Services and ask about the scope of support appropriate to your circumstances.
Reference:HDFC Mutual Fund withdrawal facility terms, used to illustrate redemption mechanics, not to recommend the product. Mutual fund investments are subject to market risks; read all scheme-related documents carefully. This article is general education, not personalised investment or tax advice.
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights