Originally published 27 August 2026. This educational article reflects its publication date; check current rules and suitability before taking action.
Many people begin financial planning by asking, “Which mutual fund should I invest in?” That question starts in the middle. A strong financial plan begins with cash flow, emergency resilience, protection and clearly defined goals. Only then can a suitable investment mix, SIP amount, tax strategy and retirement path be designed.
India offers a wide range of bank deposits, mutual funds, bonds, insurance products, retirement accounts and market-linked opportunities. More choice does not automatically create more clarity. Each product should have a job, a time horizon and a risk role within the household plan.
Quick answer: Build a financial plan by calculating net worth and monthly cash flow, creating an emergency fund, arranging appropriate health and life protection, controlling expensive debt, defining goals with dates and future costs, selecting a diversified asset allocation, investing regularly through suitable vehicles, planning taxes without letting tax benefits drive every decision, preparing for retirement and reviewing the plan periodically. Product selection follows these decisions; it does not replace them.
Step 1: Know your financial starting point
Create a one-page household balance sheet. List cash, deposits, investments, retirement accounts, property and other meaningful assets. Then list credit-card balances, personal loans, vehicle loans, home loans and other liabilities. The difference is net worth—a useful starting measure, not a measure of personal worth.
Next, review at least three to six months of bank and card statements. Separate fixed commitments, essential variable expenses, lifestyle spending, insurance, taxes, debt payments and investments. Annual costs such as school fees, maintenance, travel and premiums should be converted into monthly sinking funds rather than treated as surprises.
Calculate the investible surplus conservatively. A SIP that repeatedly fails because the budget was optimistic is less useful than a sustainable amount that can increase with income.
Step 2: Build an emergency fund before chasing returns
An emergency fund protects the plan when income stops or an urgent expense appears. Its purpose is liquidity and stability, not maximum return. The right amount depends on job security, number of earners, dependants, medical exposure, loan commitments, business volatility and access to family support.
Many households use several months of essential expenses as a planning range, while self-employed people or single-income families may prefer a larger cushion. Calculate your number from essential spending and unavoidable EMIs rather than gross income.
Keep emergency money accessible, relatively stable and separate from everyday spending. A combination of savings balance, sweep or short deposits and other suitable low-volatility options may be considered according to individual needs. Equity, long lock-ins and volatile assets are generally not substitutes for immediate emergency liquidity.
Step 3: Protect the family from high-impact risks
Health insurance
Review coverage for all family members, employer-policy dependence, room-rent conditions, waiting periods, exclusions, co-payments, network hospitals and restoration features. Medical inflation and ageing parents can make a small cover inadequate. A base policy and super top-up may be evaluated with advice.
Term life insurance
Life cover is primarily relevant when others depend on a person’s income or unpaid contribution. Estimate outstanding liabilities, future household expenses, education goals and existing assets. Pure term insurance is designed for protection; mixing every protection and investment objective can make both difficult to evaluate.
Other risks
Personal accident, disability, professional liability, property and motor risks may also matter. Insurance does not prevent an event, but it can transfer part of a financially severe risk. Disclose facts accurately and keep nominees and documents updated.
Step 4: Control expensive debt
High-interest revolving debt can compound faster than a reasonable investment plan. List every loan with balance, interest rate, EMI, remaining term, prepayment conditions and tax treatment. Pay all minimums on time and direct additional cash toward the most expensive appropriate debt while preserving emergency liquidity.
A home loan, education loan and credit-card balance should not be treated identically. Compare the guaranteed saving from prepayment with liquidity needs, goal timelines and investment risk. Avoid borrowing for discretionary consumption simply because an EMI looks affordable.
Credit health also matters. Review credit reports periodically, correct errors and do not close or open facilities only for a short-term score trick.
Step 5: Turn wishes into measurable financial goals
“Child education,” “buy a house” and “retire comfortably” need numbers and dates. For each goal, define today’s estimated cost, target year, inflation assumption, existing allocation, priority and flexibility.
A goal due in two years cannot take the same market risk as a retirement goal due in twenty years. Separate goals into short, medium and long horizons. Identify non-negotiable goals, such as basic retirement independence, and flexible goals, such as upgrading a vehicle.
Use reasonable assumptions and test difficult scenarios: lower returns, higher education cost, early retirement, career break or longer life. A plan is useful when it can show the trade-offs before reality forces them.
Step 6: Choose asset allocation before choosing products
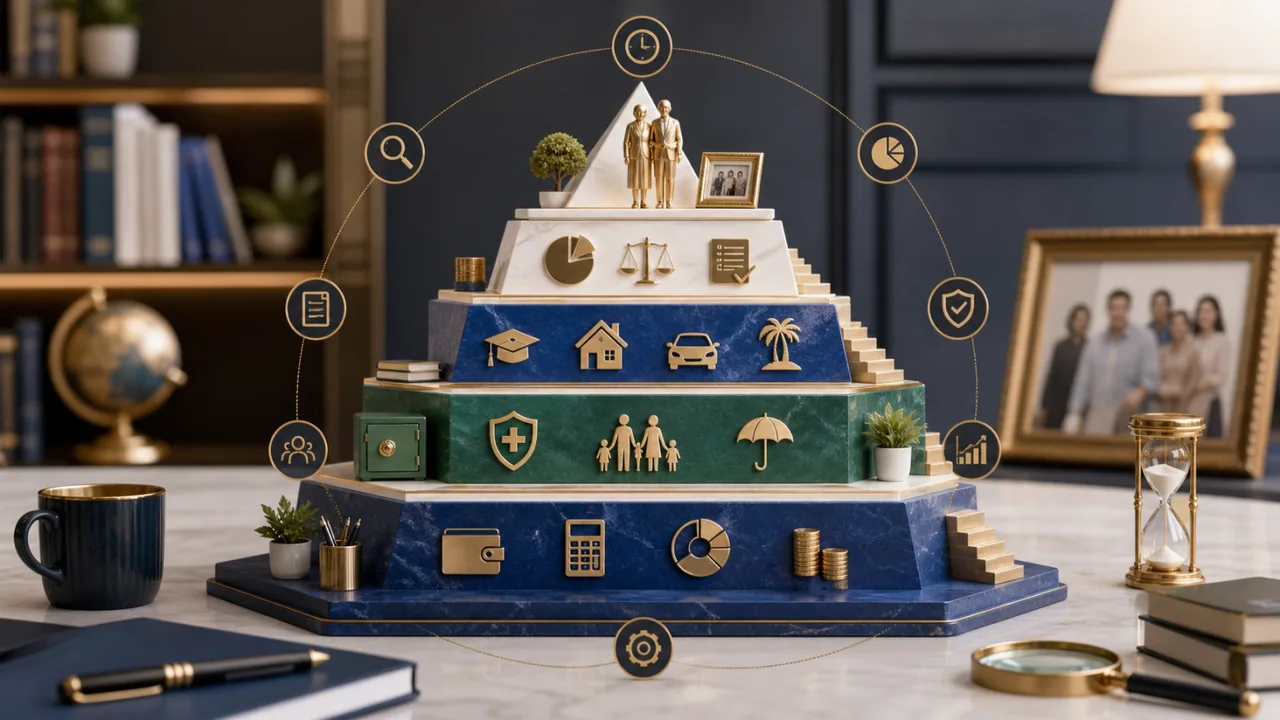
Asset allocation is the distribution among growth, stability and diversifying assets—commonly equity, debt or fixed income, cash and, where suitable, other assets. It should reflect goal horizon, capacity to absorb loss, need for liquidity and emotional tolerance for market movement.
Risk profiling is more than a questionnaire score. A person may be emotionally comfortable with volatility but unable to accept a large loss on money needed for a near-term goal. Capacity and willingness must both be considered.
Diversification reduces dependence on one company, sector, style or outcome, but it does not eliminate loss. Too many overlapping funds or products can create complexity without meaningful diversification. A simpler allocation that the family understands is easier to monitor and rebalance.
Step 7: Use SIPs as a discipline, not a guarantee
A Systematic Investment Plan is a method of investing a fixed amount at regular intervals, commonly into a mutual fund. It can automate behaviour and spread purchases across market levels. It does not guarantee profit, prevent loss or make an unsuitable fund suitable.
Choose the investment category after setting the goal and allocation. Compare objective, portfolio, benchmark, risk, cost, consistency and suitability rather than selecting only the highest recent return. Direct and regular plans have different cost and support structures; investors should understand the route used and the role and compensation of any intermediary.
Increase long-term contributions when income rises. A periodic step-up can materially improve goal funding, but only when cash flow and emergency protection remain sound. Avoid stopping a suitable long-term plan merely because markets fall; equally, do not continue blindly if the goal, fund mandate or personal circumstances change.
Step 8: Make tax planning part of the plan
Tax planning should begin with the applicable tax regime, income sources and current law. A deduction or exemption is valuable only if the product also fits liquidity, risk, cost and goal. Locking money into an unsuitable investment to save tax can create a larger problem later.
Keep records of capital gains, interest, dividends, insurance, eligible contributions and major transactions. Coordinate investment and tax advisers when circumstances involve business income, property, equity compensation, foreign assets or NRI status.
Tax rules, limits and product treatment change. Use current official information or a qualified tax professional before acting. Do not rely on an old social-media chart.
Step 9: Plan retirement as a future cash-flow problem
Retirement planning is not only choosing a retirement product. Estimate future household spending after removing work-related costs and adding healthcare, travel and support. Adjust for inflation, retirement age, longevity and existing pensions or rental income.
During accumulation, separate retirement assets from goals that will occur earlier. As retirement approaches, reduce dependence on selling volatile assets at the wrong time. A staged liquidity or income plan can support early retirement years while allowing suitable growth assets to remain invested for later decades.
After retirement, withdrawal rate, taxes, healthcare, market sequence and estate wishes require regular review. A very conservative portfolio may lose purchasing power; an overly aggressive one may create unstable withdrawals. Balance is personal.
Estate planning and family financial continuity
Nomination is useful for administration, but it may not replace a complete succession plan. Review nominations across bank, investment, insurance and retirement accounts. Consider a valid will and obtain legal advice for property, business interests, blended families, dependants with special needs or cross-border assets.
Create a secure financial inventory with account types, advisers, loan details, insurance, important documents and instructions for emergencies. Do not include passwords in an unsafe document. Ensure a trusted family member knows where the inventory and originals are kept.
Financial continuity also means that more than one person understands household cash flow and can operate essential accounts if the usual decision-maker is unavailable.
How often should a financial plan be reviewed?
A complete annual review is a useful rhythm, with interim checks after major life events: marriage, birth, job change, business start, inheritance, home purchase, relocation, retirement or a significant health event. Market movement alone does not require constant changes.
Review progress toward goals, emergency-fund adequacy, insurance, debt, asset allocation, nominations, tax impact and product performance against the reason it was selected. Rebalance when allocation moves beyond the agreed range or life circumstances change.
Performance should be evaluated after costs and taxes over an appropriate period, not against whichever asset performed best last year.
A practical first-month financial planning checklist
• Download statements and calculate net worth.
• Build a realistic monthly cash-flow table.
• Set the emergency-fund target and closing date.
• Review health and life insurance documents.
• List debts and decide the repayment order.
• Write goals with amounts, dates and priorities.
• Map existing investments to those goals.
• Identify concentration, overlap and liquidity gaps.
• Set an investment and review calendar.
Common financial planning mistakes in India
• Buying products before defining goals
• Treating employer health cover as permanent family protection
• Using every surplus rupee for a home down payment and keeping no emergency fund
• Selecting mutual funds only from recent returns
• Confusing an SIP method with low risk
• Ignoring inflation in education and retirement estimates
• Owning too many overlapping policies or funds
• Making tax-saving decisions at the final deadline
• Leaving nominees, wills and family records outdated
Frequently asked questions
Should I build an emergency fund or start an SIP first?
Basic emergency liquidity is usually foundational. Some households build it while beginning a modest long-term investment habit, but the balance depends on income stability, debt and protection. Do not expose emergency money to unsuitable volatility.
How much life insurance do I need?
Use a needs analysis covering liabilities, dependants’ future expenses, goals, existing assets and the insured person’s financial contribution. Rules of thumb are only rough starting points.
How many mutual funds should I own?
There is no ideal number. Own only enough to implement the asset allocation with genuine diversification. Additional overlapping funds can make monitoring harder without reducing risk.
What return should I assume?
Use conservative, asset-appropriate assumptions and test lower-return scenarios. Returns are uncertain; a plan should not depend on a guaranteed market outcome.
Financial planning is a system of decisions
Wealth is built not by finding one perfect product but by aligning everyday cash flow, protection and long-term investing with the life the family wants. A written plan makes trade-offs visible, creates accountability and gives market movements less power over behaviour.
Bright Vision Investment Services supports investment planning, risk profiling, portfolio management, mutual funds, insurance, retirement, NRI wealth advisory and broader family financial planning. The conversation should begin with your goals and financial position—not a product list.
Disclaimer: This article is general educational information and is not personalised investment, tax, insurance or legal advice. Mutual-fund and market-linked investments involve risk; returns are not guaranteed. Product suitability, regulations and tax treatment vary and can change. Review official documents and consult appropriately qualified professionals before investing.
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights