Originally published 11 June 2026. This educational article reflects its publication date; check current rules and suitability before taking action.
(A Complete, Easy Guide by Bright Vision Investment Services)
Hello there! If you are reading this, chances are you are a proud Non-Resident Indian (NRI). Maybe you grew up in Tamil Nadu, enjoying the lively streets of Chennai, the busy markets of Coimbatore, or the cultural beauty of Madurai. Now, you are living abroad, working hard in places like Dubai, the USA, or Singapore.
First of all, congratulations on your success! But let me ask you a question. While you are working hard for your money abroad, is your money working hard for you back home in India?
Many NRIs want to invest their money in India. India is growing fast, and one of the best ways to grow your wealth is through Mutual Funds. But the moment you decide to start, you face a big confusing question:
"Should I use an NRE account or an NRO account for my mutual fund investments?"
For over 15 years, as experts in wealth management and NRI services, we have helped hundreds of people answer this exact question. At Bright Vision Investment Services, we believe that wealth building should not be complicated. It should be simple, clear, and stress-free.
So, in this blog, I am going to explain everything to you like we are sitting together having a cup of filter coffee. No complex English words. No confusing financial terms. Just clear, simple steps to help you make the right choice.
1. The Basics: What is an NRE Account?
Think of an NRE (Non-Resident External) account as your "Foreign Income Safebox."
When you earn money outside India (like dollars, dirhams, or euros) and want to send it to India, you use an NRE account. The bank automatically changes your foreign money into Indian Rupees.
Why is an NRE Account Great?
- Zero Tax on Interest: Any interest you earn simply by keeping your money in an NRE bank account is completely tax-free in India. Yes, you heard that right! The government does not take a single rupee as tax from your NRE bank interest.
- Easy to Take Money Back: If you invest money through an NRE account and make a profit, you can easily send the whole money (your original money plus the profit) back to your foreign country. There are no limits or complicated questions asked.
Example:
Imagine you are working in Singapore. You send your salary to your NRE account in India to invest in a mutual fund. After five years, that money grows nicely. Because it came from an NRE account, you can take that entire grown amount back to Singapore without any trouble.
2. The Basics: What is an NRO Account?
Now, think of an NRO (Non-Resident Ordinary) account as your "Indian Income Manager."
Even though you live abroad, you might still make money inside India. For example:
- You might have a house in Tamil Nadu that you give for rent.
- You might get a pension in India.
- You might get dividends (profit shares) from old Indian company shares you bought long ago.
Because this money is earned inside India, the rules are different. You must keep this money in an NRO account.
Important Things to Know About an NRO Account:
- Taxes Apply: Unlike the NRE account, the interest you earn in your NRO bank account is taxed by the Indian government.
- Limits on Taking Money Back: You cannot send unlimited money from your NRO account back to your foreign country. The government allows you to send up to 1 million USD in one financial year (which is a very large amount, but there is still a limit).
3. NRE vs. NRO: Which One Should You Choose for Mutual Funds?
So, coming back to the big question: Which account should you use to buy mutual funds?
The truth is, you can use either of them! It totally depends on where your money is coming from. Let me make it very simple for you:
Choose the NRE Account if:
- You are using the salary or business income you earned outside India.
- You want the complete freedom to take your investment money and your profits back to your foreign country anytime you want.
- You want to keep your foreign earnings separate from your Indian earnings.
Choose the NRO Account if:
- You are using the money you earned inside India (like the house rent or old savings you left behind before moving abroad).
- You do not plan to take this money outside India anytime soon. Maybe you want to save this money to buy a property in Chennai later, or you want to give it to your parents living in Tamil Nadu.
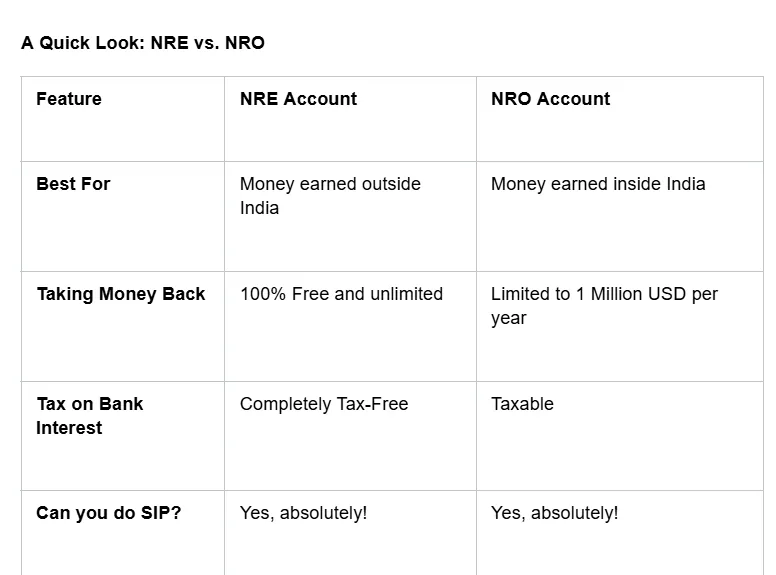
A Quick Look: NRE vs. NRO
4. The Power of SIP for NRIs
Now that you know which account to use, let us talk about the best way to invest: the SIP (Systematic Investment Plan).
What is a SIP? Imagine you have a magical piggy bank. Every month, on a fixed date, you drop a small amount of money into it. Because of the magic, the money in the piggy bank slowly starts making its own money.
When you invest consistently through a SIP, you do not have to worry about whether the stock market is high or low today. You just keep adding a little bit every month. Over 5, 10, or 15 years, this small monthly amount grows into a massive wealth pool.
At Bright Vision Investment Services, we deeply believe in the power of time. You do not need a massive amount of money to start. You just need the discipline to start now and keep going.
5. Understanding Mutual Fund Taxes for NRIs (Simply)
I know the word "tax" makes people nervous. But do not worry, I will explain it in the easiest way possible.
When you invest in Indian mutual funds and make a profit, the Indian government will ask for a small share of that profit. This is called Capital Gains Tax. It does not matter if you use an NRE account or an NRO account; the tax on your mutual fund profit is the same.
The tax depends on how long you keep your money in the mutual fund before taking it out:
- Short-Term: If you invest your money and take it out very quickly (usually within 1 year for share market funds), the government sees it as a short-term profit. The tax rate for this is a little higher.
- Long-Term: If you are a patient investor and keep your money in the fund for more than 1 year, it is a long-term profit. The government loves long-term investors! So, the tax rate is lower. In fact, for equity funds, your first ₹1 Lakh profit in a year is completely tax-free!
Friendly Advice: Always invest with a long-term mindset. It is the best way to build serious wealth and pay less tax.
[Image Prompt: A visually appealing, ultra-realistic image of a happy professional in a modern office space in Chennai, wearing a sharp suit, warmly shaking hands with an NRI client. The sunlight is coming through a glass window. The mood is trustworthy, successful, and bright.]
6. How to Start Your NRI Investment Journey Today
Starting your mutual fund journey from abroad is much easier than it used to be. Here are the simple steps:
Step 1: Update Your Status
If you recently moved abroad, inform your Indian bank to change your normal savings account into an NRO account. You cannot hold a normal resident savings account once you become an NRI. Also, open a new NRE account to send your foreign salary.
Step 2: Complete Your NRI KYC
KYC stands for "Know Your Customer." It is a simple one-time paperwork process. You just need to submit your passport copy, foreign address proof, and PAN card. Because everything is digital now, you can do this entirely online from your phone or laptop!
Step 3: Connect Your Bank Account
Link your NRE or NRO bank account to your mutual fund investment account.
Step 4: Pick the Right Funds and Start!
There are hundreds of mutual funds out there. Some are safe and slow, others are fast and carry more risk. Choosing the right one can be confusing. That is where experts come in.
7. Why Choose Bright Vision Investment Services?
If you are an NRI looking to build wealth in India, you need someone you can trust. You need someone who understands the local rules of India and the unique challenges you face while sitting thousands of miles away.
At Bright Vision Investment Services, we specialize in high net worth individual services, portfolio management, and guided investment planning. We have a special focus on helping our people from Tamil Nadu. We understand your culture, your goals, and your dreams of building a safe future for your family back home.
Our future goal is to help 500 individuals become Crorepathis. We believe this is completely possible if you follow the right guidance, stay patient, and invest consistently.
We handle all the heavy lifting for you:
- We help you complete your NRI KYC without any headache.
- We analyze your goals (like buying a house in India, children's education, or your retirement) and pick the exact mutual funds that match your needs.
- We monitor your portfolio, making sure your hard-earned money is always on the right track.
8. Final Thoughts
Living away from your motherland is a big sacrifice. You miss the festivals, the food, and the family gatherings. But you do it to give yourself and your loved ones a better life. Do not let your hard work sit idle in a normal bank account earning nothing.
Whether you choose an NRE account for your foreign earnings or an NRO account for your Indian earnings, the most important step is simply taking the first step. Start your SIP, stay focused, and watch your wealth grow.
We are here to hold your hand through this journey. Let us build your bright future together!
Mutual Fund Disclaimer:
Mutual Fund investments are subject to market risks, read all scheme-related documents carefully. The information provided in this blog is for educational and informational purposes only and does not constitute any guarantee of returns, assured financial growth, or promises of specific outcomes. Bright Vision Investment Services adheres strictly to all SEBI guidelines and regulations. Past performance of mutual funds is not an indicator of future results. Please consult with a registered financial advisor before making any investment decisions.
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights