Originally published 7 September 2026. This educational article reflects its publication date; check current rules and suitability before taking action.
Living abroad can improve income while making financial life more complicated. An NRI may earn in one currency, support family in India, own property, maintain several bank accounts, invest across countries and plan to return years later. Without coordination, accounts can have the wrong residential status, investments can overlap, nominations can be outdated and tax reporting can be missed in one jurisdiction.
People searching for NRI financial planning in India usually need a system rather than a product list. Banking, tax residency, cash flow, insurance, investments, estate planning and return-to-India decisions influence one another. This guide explains the questions an NRI family should organise with authorised financial, tax and legal professionals.
Quick answer: Update residency status with every institution, separate NRE, NRO and foreign-currency needs, maintain emergency reserves in the right currencies, define India and overseas goals, build a diversified portfolio under applicable investment rules, coordinate tax reporting in both countries, and start return-to-India planning before the move.
1. Build a cross-border financial inventory
List every bank, deposit, mutual fund, security, retirement plan, insurance policy, loan, property, business interest and digital asset in India and abroad. Record ownership, currency, current value, nominee or beneficiary, maturity, tax status and document location. Include employer benefits and old accounts that receive no attention.
Create a one-page family balance sheet and annual cash-flow view. Convert values using a consistent reference rate for planning, while remembering that actual future exchange rates will differ.
2. Determine residential status separately under each law
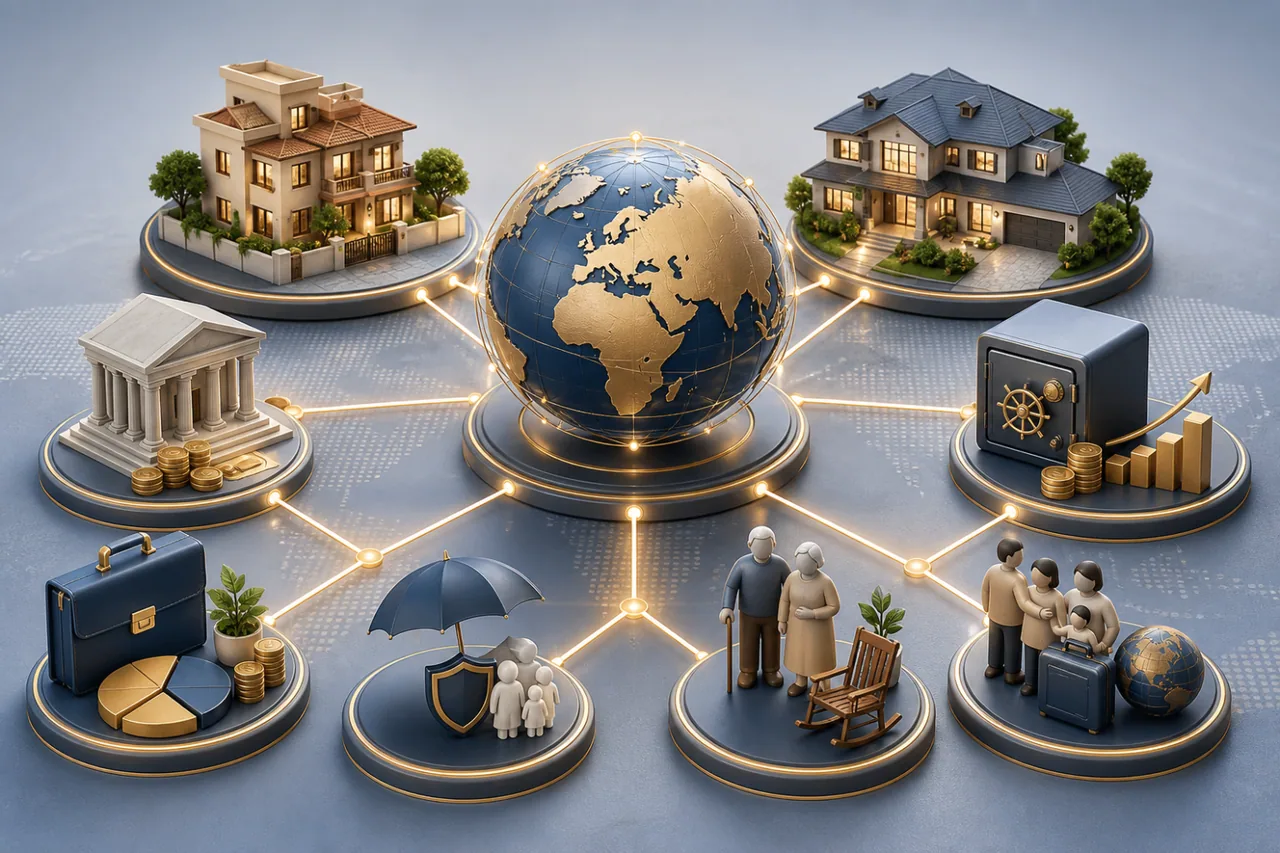
Residence for Indian income tax is determined under statutory tests that can change and may differ from foreign immigration status or FEMA treatment. Days of stay, citizenship, income and exceptional rules can matter. A person can face different classifications in two countries and may need treaty analysis.
Do not label yourself NRI forever because you once moved abroad. Review status each financial year and whenever travel or employment changes. Use a qualified tax adviser for the relevant countries.
3. Regularise Indian bank accounts
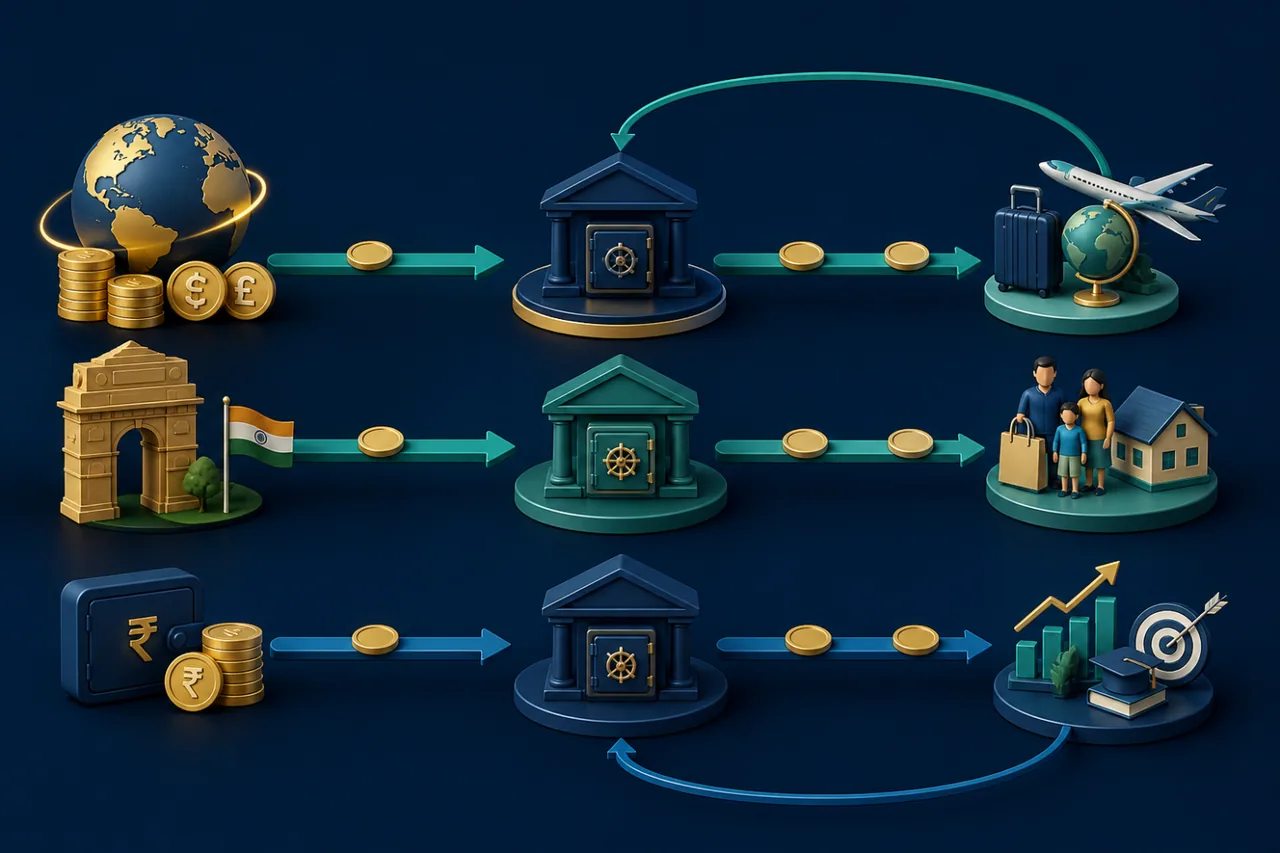
Ordinary resident savings accounts generally should not continue unchanged after becoming non-resident. NRE, NRO and foreign-currency deposit accounts serve different purposes and have different repatriation and tax treatment. Current Reserve Bank rules and bank documentation should guide conversion and operation.
NRE account
Commonly used for eligible overseas earnings remitted to India, with rupee denomination and repatriation features under current rules. Exchange-rate movement affects value in the earning currency.
NRO account
Commonly used to manage eligible Indian income such as rent, dividends or local receipts. Tax deduction and repatriation documentation may apply.
Foreign-currency deposits
These may reduce direct rupee conversion exposure for defined tenures, subject to product and regulatory conditions. Compare liquidity, currency, return and purpose rather than chasing a headline rate.
4. Maintain emergency funds in two locations
An NRI household may need immediate money where it lives and money in India for parents, property or planned commitments. Hold liquid reserves in the currency and account from which the expense will be paid. Consider job stability, visa dependence, health coverage, family support and relocation risk.
Do not place the entire emergency fund in long-term or market-linked products. Accessibility and operational authority matter during a crisis.
5. Separate goals by currency and country
Define goal amount, date, currency and priority. An Indian home purchase, overseas education goal and retirement split across two countries should not use the same inflation or currency assumption. Estimate cash flows in the goal currency and build reasonable buffers.
Decide whether retirement is likely in India, abroad or flexible. The answer changes expected expenses, healthcare, housing, tax, social benefits and required currency exposure.
6. Review Indian investment eligibility
Products available to residents may have different onboarding, transaction or repatriation rules for NRIs. Update KYC, address, tax residence, bank mandates and FATCA or CRS declarations as required. Some fund houses, brokers or products may restrict investors from particular countries.
Never route investments through an outdated resident account to avoid paperwork. Correct classification protects future withdrawals and reporting.
7. Design asset allocation before selecting products
Set the mix of equity, fixed income, cash, property and other assets from goal horizon, risk capacity, currency and existing exposure. An NRI employed in one industry and owning Indian property already has concentrated risks. Buying multiple similar funds does not necessarily diversify them.
Separate growth assets for long horizons from stable assets for near-term commitments. Rebalance using new contributions, maturities and controlled transactions rather than reacting to every market movement.
8. Understand currency risk
A rupee investment can rise locally but deliver a different result when converted to another currency. Currency movement can help or hurt and should not be forecast with false precision. Match part of the portfolio to future spending currency and diversify where regulations and suitability permit.
Avoid converting large sums merely because of a short-term exchange-rate opinion. Use a planned remittance schedule tied to goals and liquidity.
9. Coordinate tax reporting
Indian income can include rent, capital gains, interest, business income and other receipts. Tax deduction at source may not equal final liability. The country of residence may also tax worldwide income and require foreign-account or asset disclosures. Treaties and foreign tax credits can reduce double taxation when correctly applied, but documentation and timing matter.
Maintain purchase records, improvement costs, tax certificates, bank statements, remittance documents and residency evidence. Engage advisers who understand both jurisdictions or can coordinate with one another.
10. Review real estate as part of the portfolio
Indian property creates concentration, maintenance, vacancy, legal, tax and management responsibilities. Measure net rental yield after expenses and compare it with the family’s goals. Keep title, approvals, tax receipts, lease, insurance and property-manager authority organised.
Sale by an NRI can involve tax deduction and repatriation procedures. Plan before signing a transaction rather than after receiving the advance.
11. Protect the family across countries
Review health, life, disability, travel and liability coverage in the country of residence and India. Employer insurance may end with a job or visa. Indian health insurance can be relevant for a planned return or dependent parents, but waiting periods, network and claim terms need evaluation.
Life cover should relate to liabilities, dependants, future goals and existing assets. Disclose residence, travel and occupation accurately to insurers.
12. Update nominees, wills and authority
Nomination and legal inheritance are not always the same. Cross-border estates can involve different succession, probate and tax systems. Review wills, nominees, beneficiaries, joint holdings and powers of attorney with qualified legal professionals in the relevant jurisdictions.
Maintain a secure family information sheet: adviser contacts, account list, insurance, property documents and emergency instructions. Do not share passwords insecurely.
13. Plan the return to India early
Begin before the flight is booked. Model housing, school, healthcare, transport, family support and income transition. Review the tax treatment and timing of foreign accounts, retirement plans, stock compensation and asset sales. Residency classifications can change after return and may affect deposit or income treatment.
Keep enough foreign-currency liquidity for obligations that remain abroad. Update bank, broker, insurer and employer records as status changes. A return plan should include career uncertainty and not assume immediate income continuity.
Annual NRI review checklist
• Recalculate residential status and travel days.
• Update KYC, address and tax-residence declarations.
• Review NRE, NRO and foreign accounts for purpose and liquidity.
• Measure progress toward goals in their own currencies.
• Rebalance investments and control concentration.
• Prepare tax and foreign-asset reporting documents.
• Review insurance, nominees, wills and property records.
• Revisit return-to-India assumptions and timeline.
Managing financial responsibilities for family in India
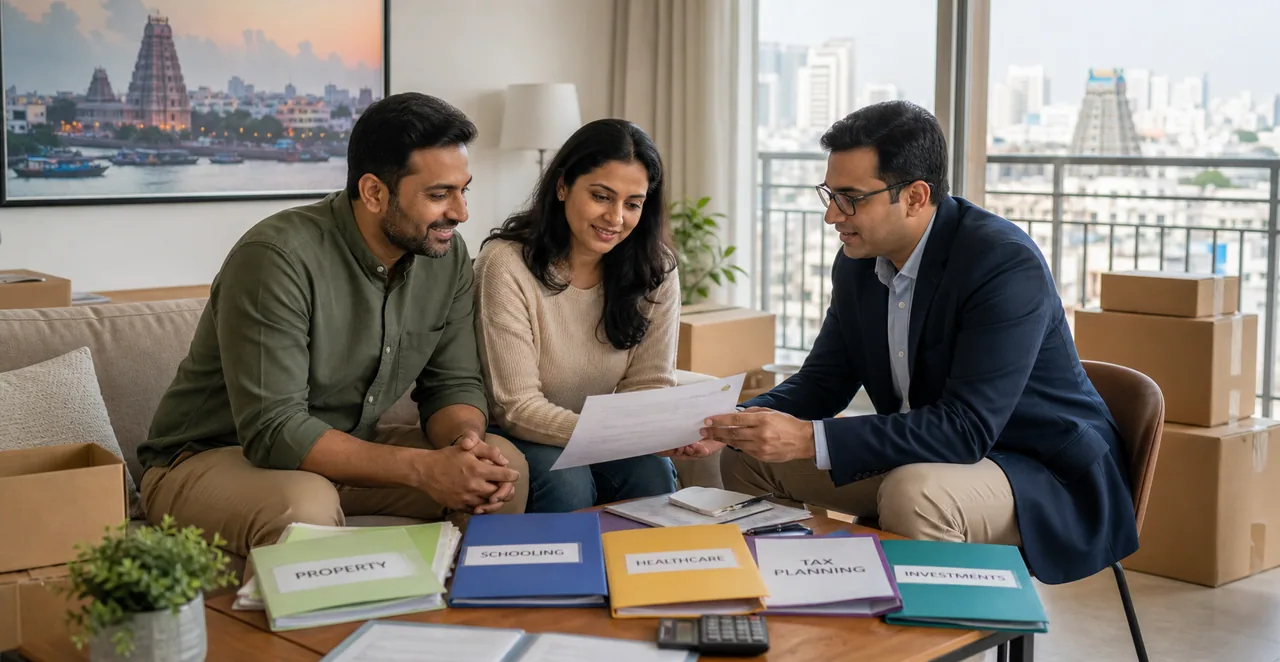
Many NRIs support parents, maintain a Chennai home, pay insurance or fund education in India. Convert these commitments into an annual calendar rather than handling every request as an emergency. Keep a dedicated account for predictable Indian expenses, define who may operate it, and review standing instructions. Parents should know which expenses are covered and whom to contact if the NRI cannot be reached.
Medical support deserves a separate plan. Record health insurance, preferred hospitals, emergency contacts and an accessible reserve. Property expenses should include maintenance, tax, repairs and vacancy—not only the loan EMI. Clear family communication reduces duplicate policies, missed payments and unsuitable investments purchased under pressure.
Questions to ask an NRI financial adviser
• What registrations or authorisations cover the recommended service?
• How are fees, commissions and conflicts disclosed?
• How will India and overseas assets be viewed together?
• Which recommendations require separate tax or legal advice?
• How will performance, risk and goal progress be reported?
• What happens to the plan when residency changes?
Frequently asked questions
Can an NRI continue a normal resident savings account?
Account status should be updated according to current banking and FEMA rules. Contact the bank promptly after residential status changes.
Are NRE and NRO accounts interchangeable?
No. They serve different receipt, tax and repatriation purposes. Use the account that matches the source and intended use of funds.
Should NRIs invest only in India?
Portfolio location should reflect goals, currencies, regulations, taxes and existing exposure. Concentrating every asset in one country can create avoidable risk.
When should return planning begin?
Ideally one to three years before a planned move, and earlier when pensions, business interests, stock compensation or property transactions are involved.
One family needs one coordinated plan
NRI financial planning is a continuing process of keeping accounts, investments, taxes and family decisions aligned across borders. Product selection comes after residency, goals, cash flow and currency are understood.
Bright Vision Investment Services supports clients in Chennai, across India and abroad with goal-based financial planning and investment guidance. NRI families should combine investment advice with qualified tax and legal advice for their countries and personal circumstances.
Disclaimer: This article is general educational information and not investment, tax or legal advice. Regulations, tax rules and product eligibility change. Investments are subject to risk; obtain personalised advice from appropriately authorised professionals.
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights