Originally published 13 December 2025. This educational article reflects its publication date; check current rules and suitability before taking action.
Why This Matters to You
Whether you're sipping filter coffee in Mylapore or closing deals in Manhattan, your money should work as hard as you do. For Indians living abroad or planning their global journey, managing investments isn't just about numbers—it's about building a bridge between your dreams and reality.
Think of your portfolio like a well-balanced thali. Just as you wouldn't fill your plate with only rice or only sambar, your investments need the right mix of ingredients to satisfy your financial hunger. Let's explore how to create this perfect balance.
Understanding Your Financial Journey
What Exactly is Goal-Based Investing?
Imagine you're planning a road trip from Chennai to Ooty. You wouldn't just start driving randomly, right? You'd:
- Decide your destination
- Check your fuel
- Plan your route
- Pack accordingly
- Set a timeline
Goal-based investing works exactly the same way. Instead of throwing money at random investments, you start with where you want to go and work backwards.
The Three Pillars of Smart Investing
1. Your Goals (The Destination)
- Short-term: That dream vacation to Bali (1-3 years)
- Medium-term: Down payment for your Chennai apartment (3-7 years)
- Long-term: Comfortable retirement watching sunsets (7+ years)
2. Your Risk Appetite (The Vehicle)
- Conservative: Like a sturdy Ambassador car—slow but steady
- Moderate: Like a reliable sedan—balanced performance
- Aggressive: Like a sports car—fast but needs careful handling
3. Your Timeline (The Speed) The longer your journey, the more scenic routes (riskier investments) you can afford to take.
The NRI Investment Challenge (And How to Win It)
Why NRIs Face Unique Hurdles
Living abroad while managing Indian investments is like trying to cook biriyani through a video call—possible, but tricky. Here's what makes it challenging:
Currency Confusion: Your salary in dollars, expenses in rupees, and investments in both? The exchange rate dance can make or break your returns.
Tax Tangles: Two countries, two tax systems, and a lot of paperwork. Without proper guidance, you might pay more tax than necessary.
Account Acrobatics: Regular savings accounts don't work for NRIs. You need special NRO or NRE accounts—and knowing which one fits your needs is crucial.
Distance Dilemmas: Managing investments from another timezone means you might wake up to market changes that happened while you slept.
Your Investment Toolkit: What Goes Where?
Understanding Investment Instruments (In Simple Terms)
Systematic Investment Plans (SIPs)
Think of SIP like your monthly phone recharge. Instead of putting a huge amount once, you invest small amounts regularly.
Real Example: Priya, a software engineer in Singapore, invests ₹10,000 monthly through SIP. Over 10 years, even with market ups and downs, her disciplined approach built a corpus of ₹18 lakhs (assuming 12% average returns).
Why SIPs Work Magic:
- You invest whether markets are high or low
- When prices drop, you buy more units
- When prices rise, your existing units grow
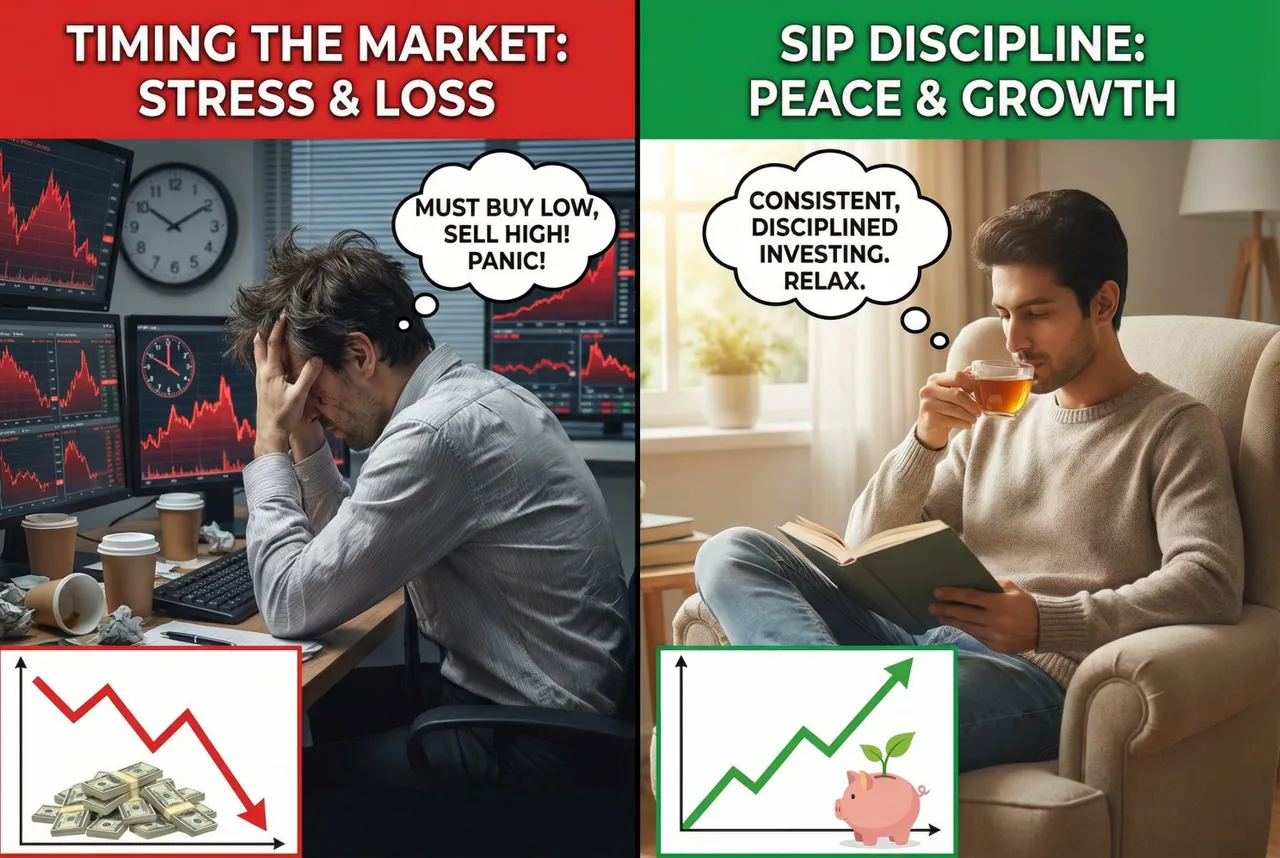
- Removes the stress of "timing the market"
Equity Investments
These are like planting mango trees. Initially, you wait patiently, water regularly, and then enjoy sweet fruits for years.
Best for: Long-term goals (10+ years) Risk: Higher volatility Potential Returns: 12-15% annually (historically)
Debt Instruments
Think of these as fixed deposits' sophisticated cousins—safer than equity, better returns than traditional FDs.
Best for: Short to medium-term goals Risk: Low to moderate Potential Returns: 6-9% annually
Gold Investments
Your grandmother wasn't wrong about gold! Modern gold investments (digital gold, gold ETFs) give you the security without the storage headache.
Creating Your Perfect Portfolio Mix
The Age-Old Formula (With a Modern Twist)
The Classic Rule: Equity percentage = 100 minus your age
If you're 30, invest 70% in equity and 30% in debt. If you're 50, flip it to 50-50.
But this is just a starting point. Your actual mix depends on:
Your Income Stability: Government job? Take more risks. Business owner? Stay balanced.
Your Existing Assets: Already own property? Can be more aggressive with other investments.
Your Dependents: Supporting parents or kids? Need more safety nets.
Your Goals Timeline: Daughter's education in 5 years? Different strategy than retirement in 25 years.
Sample Portfolios for Different Life Stages
Rajesh (28, IT Professional in USA)
- Goal: Buy apartment in Chennai in 7 years
- Income: Stable
- Portfolio Mix: 60% Indian equity mutual funds 20% US index funds 15% Debt funds 5% Gold
Meera (45, Business Owner in Dubai)
- Goal: Daughter's education + Retirement planning
- Income: Variable
- Portfolio Mix: 40% Equity 40% Debt instruments 10% Real estate funds (REITs) 10% Gold
The NRI Account Maze: Simplified
Which Account Do You Need?
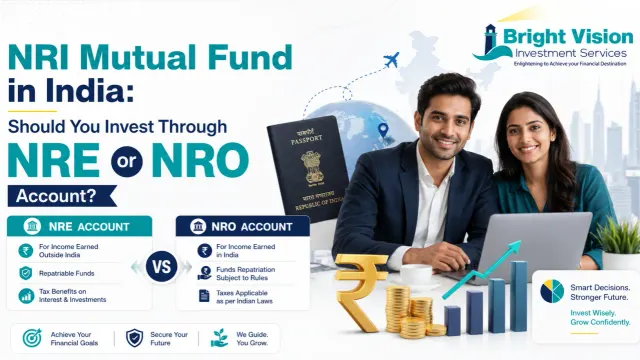
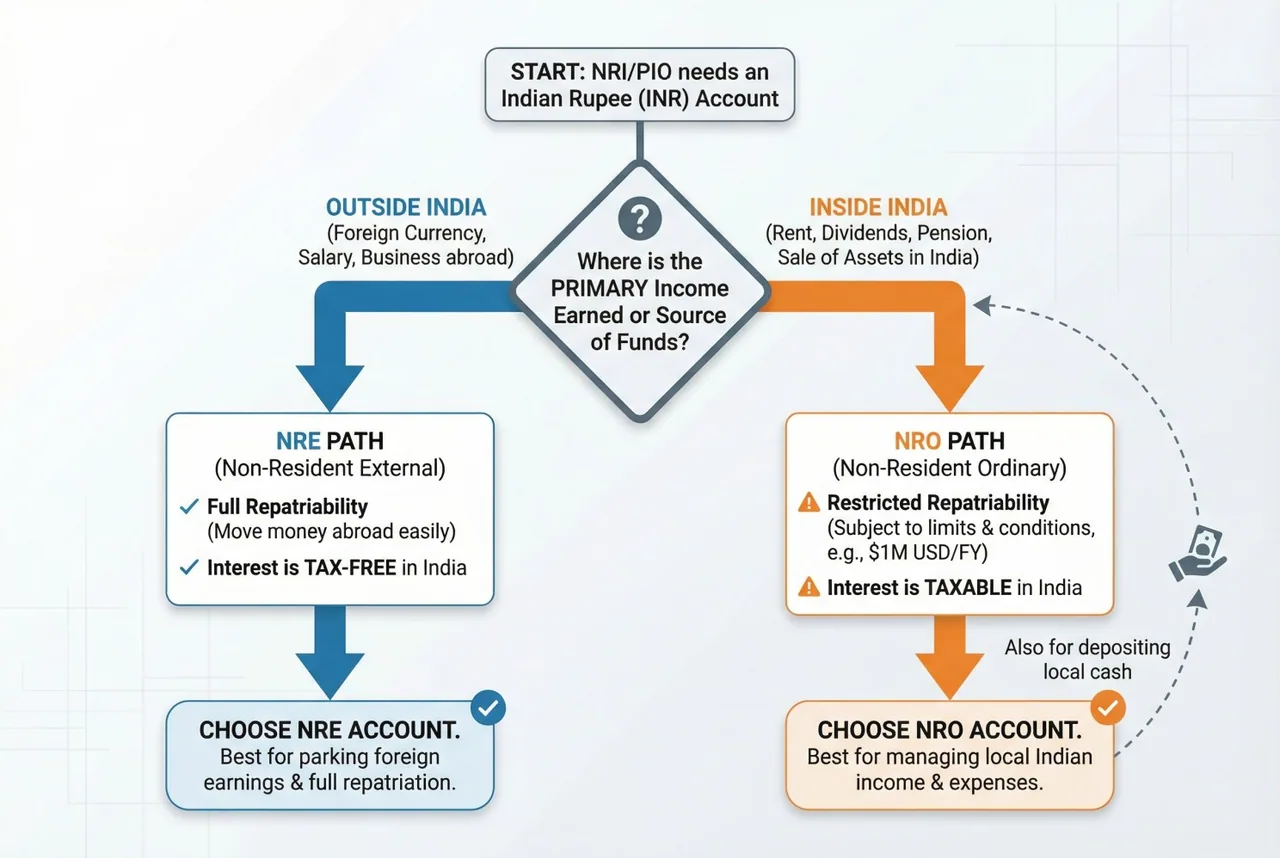
NRE Account (Non-Resident External)
Use this for: Transferring your foreign earnings to India Tax benefit: Interest earned is tax-free in India Repatriation: Can take money back abroad freely Think of it as: Your "foreign money parking spot"
NRO Account (Non-Resident Ordinary)
Use this for: Managing income earned in India (rent, dividends, pension) Tax benefit: Interest taxed in India Repatriation: Limited to USD 1 million per year Think of it as: Your "Indian income manager"
The Chennai Connection: Managing these accounts from abroad requires proper documentation. Having a professional team in your hometown (like Chennai) who understands both SEBI guidelines and international regulations makes this process smooth.
Portfolio Management: Beyond Just Buying and Holding
The Four Seasons of Portfolio Care
Spring (Review Season - Quarterly)
- Check if investments are growing as expected
- Review if goals have changed
- Ensure adequate diversification
Summer (Rebalancing - Yearly) When equity grows too much, book some profits and move to debt. When debt accumulates, move some to equity.
Example: Started with 60-40 equity-debt. After a great year, it became 75-25. Time to rebalance back to your target allocation.
Autumn (Tax Planning - Before March)
- Utilize tax deductions under Section 80C
- Plan for LTCG/STCG tax
- Document everything for dual taxation
Winter (Big Picture Review - Annually)
- Are you on track for major goals?
- Do you need to increase/decrease investments?
- Life changes (marriage, kids, job change)?
For High Net Worth Individuals: Stepping Up Your Game
When Your Portfolio Grows Beyond Basics
Once your investments cross ₹1 crore, you're not just investing—you're wealth building. This requires:
Portfolio Management Services (PMS)
- Customized strategies for your unique situation
- Direct equity management
- Higher minimum investment (typically ₹50 lakhs+)
- Personalized attention to your financial goals
Alternative Investment Funds (AIFs)
- Real estate funds
- Private equity opportunities
- Hedge funds
- Venture capital options
Estate Planning
- Succession planning
- Trust formation
- Will and nominations
- Multi-generational wealth transfer
The Tamil Nadu Advantage: Why Location Matters
Chennai's Unique Investment Landscape
Being based in Chennai offers specific advantages:
Strong Manufacturing Sector: Opportunities in automobile, technology, and healthcare investments
Growing IT Hub: Thriving startup ecosystem for equity investors
Real Estate Stability: Compared to Mumbai or Delhi, more affordable and steady appreciation
Cultural Savings Mindset: Tamil households have historically high savings rates—leverage this strength
Educational Excellence: With IIT Madras and other premier institutions, strong foundation for financial literacy
Local Opportunities Global Indians Miss
Many NRIs overlook Tamil Nadu-specific investments:
- State government bonds
- Tamil Nadu-focused mutual funds
- Regional real estate opportunities
- Chennai's emerging startup scene
Common Mistakes (And How to Avoid Them)
The "Set and Forget" Trap
Suresh invested ₹20 lakhs in 2015 and never reviewed. In 2020, he discovered one fund had become 45% of his portfolio. A market correction wiped out significant gains.
Solution: Review quarterly, rebalance yearly.
The "Home Bias" Problem
Investing only in India because you're Indian? That's like eating only idli-sambar because you're from Chennai—delicious but not nutritionally complete!
Solution: Diversify globally. Consider international funds or US market exposure.
The "Tax Amnesia" Error
Many NRIs forget about tax implications in both countries.
Solution: Work with advisors who understand DTAA (Double Taxation Avoidance Agreement).
The "Timing the Market" Illusion
Trying to predict market tops and bottoms? Even experts get it wrong.
Solution: Stay invested. Time IN the market beats TIMING the market.
Compliance and Regulations: Staying on the Right Side
SEBI Guidelines You Should Know
For NRI Investments:
- Portfolio Investment Scheme (PIS) for direct equity
- Limits on investment in certain sectors
- Reporting requirements for foreign assets
- Documentation for repatriation
For Regular Investors:
- KYC (Know Your Customer) compliance
- PAN card mandatory for investments
- Nomination facilities
- Annual portfolio statements
Working With Regulated Advisors
Always ensure your investment advisor is:
- SEBI registered
- Has transparent fee structure
- Provides regular documentation
- Follows proper compliance procedures
Professional firms operating in cities like Chennai must adhere to strict SEBI guidelines, providing you security and accountability.
The Digital Revolution in Indian Investing
Technology Making Life Easier
For Global Indians:
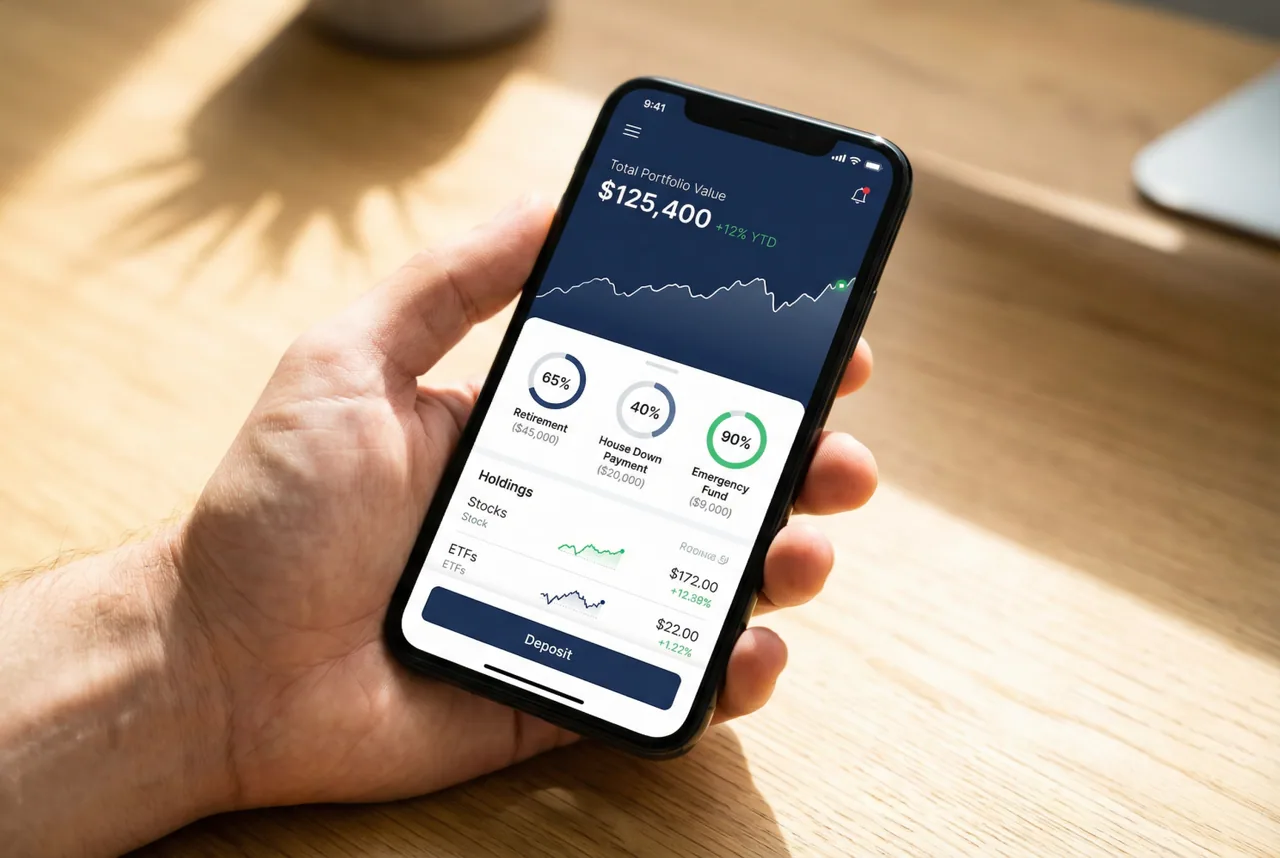
- Mobile apps for instant portfolio tracking
- Video KYC from anywhere in the world
- Digital signatures for paperwork
- Real-time currency conversion tracking
For Everyone:
- AI-driven portfolio recommendations
- Automated rebalancing
- Tax harvesting tools
- Goal-based calculators
Building Your Investment Team
Who You Need in Your Corner
SEBI Registered Investment Advisor
- Creates your financial plan
- Recommends suitable investments
- Provides ongoing guidance
Tax Consultant
- Handles Indian tax returns
- Manages foreign tax credits
- Ensures DTAA compliance
Chartered Accountant
- NRE/NRO account guidance
- Repatriation documentation
- Annual audits if required
Local Representative (If you're an NRI)
- Someone in Chennai or your hometown
- Manages physical paperwork
- Provides local market insights
Having a dedicated team based in Chennai offers advantages—they understand local opportunities while managing your global portfolio.
Real Success Stories: Learning From Others
Case Study 1: The Systematic Investor
Name: Venkat, Mechanical Engineer in Germany Age: 35 Goal: Financial freedom by 50
Strategy:
- Started SIP of ₹25,000/month in 2015
- Increased by 10% every year
- Mix of large-cap, mid-cap, and international funds
- Never stopped, even during market crashes
Result: After 9 years, portfolio value crossed ₹60 lakhs. On track to achieve goal.
Key Lesson: Consistency beats intelligence in investing.
Case Study 2: The Diversified Planner
Name: Lakshmi, Doctor in London Age: 42 Goal: Children's education + Retirement home in Chennai
Strategy:
- 50% in Indian equity mutual funds
- 20% in UK pension scheme
- 15% in debt funds
- 10% in gold
- 5% in REITs
Result: Balanced growth with downside protection. Smooth sailing even during COVID crash.
Key Lesson: Diversification is your friend during tough times.
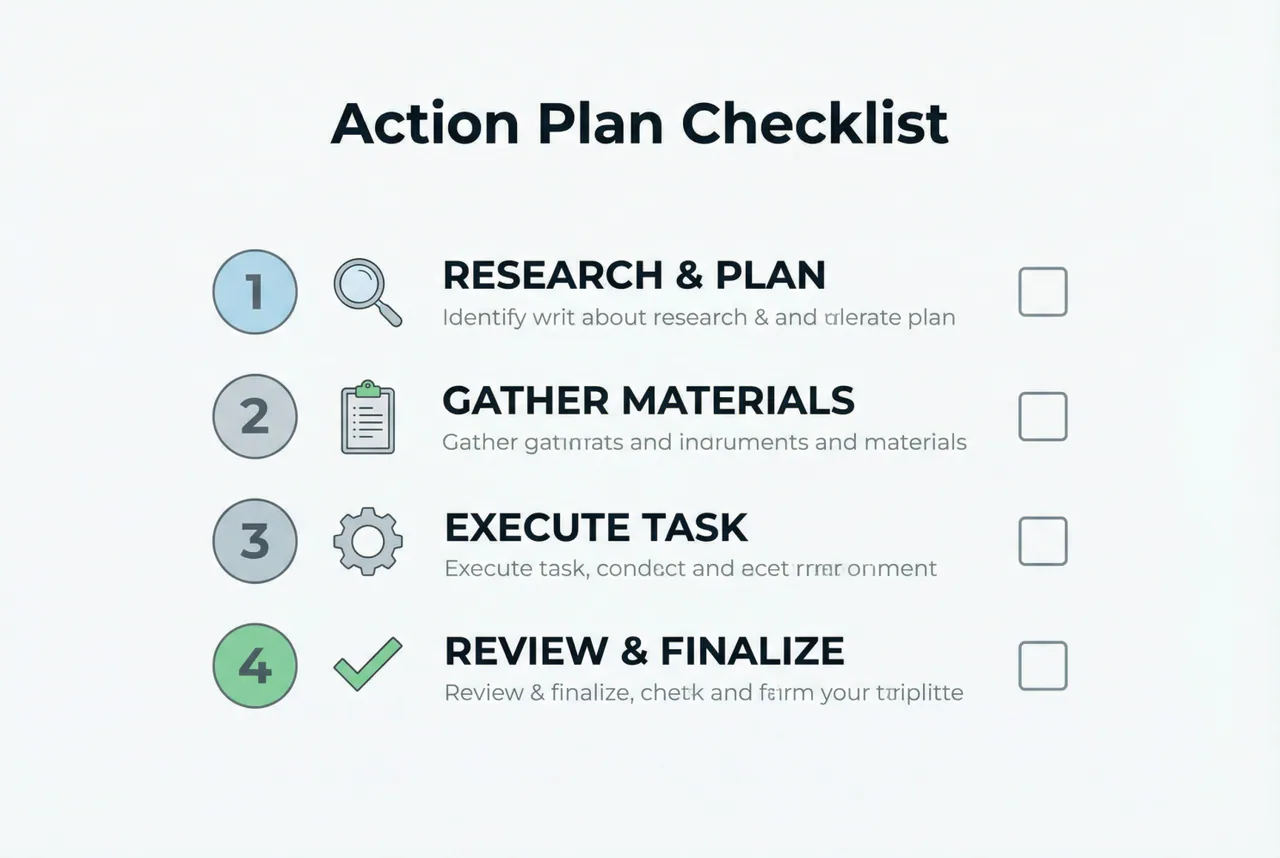
Your Action Plan: Getting Started Today
Step 1: Define Your Goals (This Week)
Grab a notebook. Write down:
- What do you want to achieve?
- When do you need the money?
- How much will you need?
Be specific: Not "comfortable retirement" but "₹5 crore corpus by age 60"
Step 2: Assess Your Current Position (This Month)
- List all current investments
- Calculate net worth
- Identify gaps
- Determine risk appetite
Step 3: Create Your Strategy (This Month)
- Decide asset allocation
- Select investment instruments
- Set up SIPs
- Open necessary accounts (NRE/NRO if needed)
Step 4: Execute and Monitor (Ongoing)
- Start investments
- Set calendar reminders for reviews
- Track progress quarterly
- Rebalance annually
- Adjust for life changes
The Chennai Connection: Why Local Expertise Matters
Understanding Regional Nuances
While investment principles are universal, local expertise adds value:
Time Zone Advantage: A team in Chennai operates during Indian market hours, making real-time decisions when needed.
Cultural Understanding: Advisors who understand Tamil Nadu's investment culture, family structures, and long-term planning mindset.
Physical Presence: For NRIs, having someone who can handle documentation, property verifications, or family financial needs.
Regulatory Navigation: Local teams stay updated with state-specific opportunities and regulations.
Network Access: Connections with local chartered accountants, lawyers, and banks for comprehensive service.
Professional investment advisory services operating from cities like Chennai bring this local-global balance—understanding your roots while planning for your global future.
Frequently Asked Questions
Q: How much should I invest monthly? A: Start with at least 20% of your income. Increase as your income grows.
Q: Can NRIs invest in Indian mutual funds? A: Yes! Most mutual funds are NRI-friendly. You need PIS permission for direct equity.
Q: What's the minimum amount to start? A: SIPs can start as low as ₹500. No excuse to delay!
Q: Should I invest in India or abroad? A: Both! Diversify across geographies for optimal risk-return balance.
Q: How often should I check my portfolio? A: Monthly for awareness, quarterly for action. Daily checking causes stress, not wealth.
Q: What returns can I expect? A: Equity: 10-15% (long-term), Debt: 6-9%, Balanced: 8-12%. Remember, past performance doesn't guarantee future results.
The Bigger Picture: Financial Independence
Beyond Just Money
Investing isn't just about accumulating wealth—it's about:
Freedom: The choice to work because you want to, not because you have to
Security: Peace of mind that your family is protected
Legacy: Building something that outlasts you
Impact: Ability to support causes you care about
Experiences: Funding the life you dream of living
For global Indians, it's also about:
- Staying connected to your roots
- Supporting family back home
- Contributing to India's growth story
- Creating options for returning
Taking the Next Step
Your Investment Journey Starts Now
You don't need to be a financial expert to start building wealth. You need:
- Clear goals
- Basic understanding
- Disciplined approach
- Regular guidance
- Patience
Whether you're in Chennai or Chicago, Coimbatore or California, your investment journey is personal yet universal.
The best time to start was yesterday. The second-best time is today.
Important Disclaimer
This article is for educational purposes only and should not be considered as investment advice. All investment decisions should be made after consulting with SEBI-registered investment advisors. Past performance of investments doesn't guarantee future returns. Investments in securities market are subject to market risks.
The examples provided are hypothetical and for illustration purposes only. Actual results may vary based on market conditions, investment timing, and individual circumstances.
Please read all scheme-related documents carefully before investing. Ensure you understand the risks involved and assess whether the investment objectives align with your financial goals.
Connect and Grow
Building wealth is not a solo journey. It requires knowledge, discipline, and sometimes, professional guidance.
For global Indians navigating the complex world of investments—whether you're managing portfolios from abroad or planning your financial future from Chennai—having the right partner makes all the difference.
Remember: Your money should work as hard as you do, and your portfolio should reflect your dreams, not just your bank balance.
The path to financial freedom is not a sprint—it's a well-planned marathon. Start your journey today.
About the Author: This article is brought to you by investment professionals who understand the unique challenges faced by global Indians and local investors alike. Our expertise lies in creating customized investment strategies that bridge geographical boundaries while respecting regulatory frameworks and individual goals.
#InvestmentPlanning #NRIInvesting #ChennaiFinance #GoalBasedInvesting #WealthManagement #FinancialFreedom #SIPInvesting #GlobalIndians #PortfolioManagement #TamilNaduInvestors #SmartInvesting #FinancialPlanning
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights