Originally published 7 October 2026. This educational article reflects its publication date; check current rules and suitability before taking action.
A mutual fund discussion can become confusing when several different charges are described simply as “fees.” One person mentions the expense ratio. Another warns about exit load. A third talks about tax. These are different questions, and combining them into one percentage makes an investment harder to understand.
For Indian investors comparing schemes or planning a withdrawal, a useful starting point is to separate ongoing fund expenses from a charge that may apply when units are redeemed. Then check the actual scheme documents, the exact plan and the dates relevant to your investment.
Quick answer: The expense ratio relates to operating expenses within a mutual fund scheme. Exit load, where applicable, affects redemption under specified conditions. Neither figure alone tells you whether a scheme suits your goal, time horizon or capacity for loss.
Start with the exact investment, not a remembered fund name
Write down the complete scheme name, plan and option shown on the official record. Similar names can refer to different products or arrangements. A screenshot that cuts off the plan name may create a misleading comparison before you have even reached the cost figures.
Next record the date on which you checked the information and the official source. This is a simple habit with a practical benefit: a number copied months ago should not silently become the basis of a decision today. Save the relevant document or official link alongside your notes.
If you already hold the investment, keep the transaction record available. A fresh purchase enquiry and a redemption enquiry require different details. Tell the person helping you which question you are trying to answer, rather than asking whether a fund is simply “cheap.”
What the expense ratio actually describes
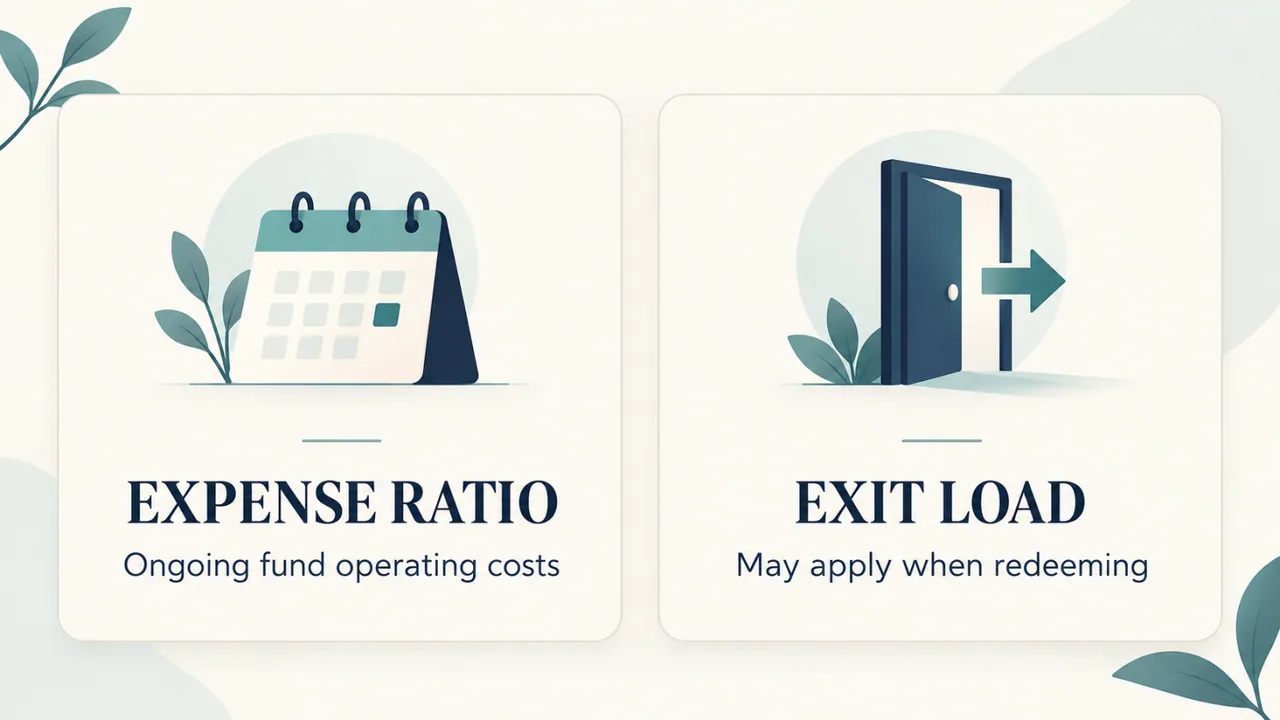
AMFI describes the total expense ratio, or TER, as operating costs involved in running and managing a mutual fund scheme. These can include investment management, administration and other permitted expenses. AMFI also explains that the disclosed daily NAV reflects expenses already deducted.
That means the expense ratio should not be imagined as a separate shopping bill arriving once a year. It forms part of the fund's operation and affects the value reported through the scheme. For the source explanation and current disclosures, begin with AMFI’s expense-ratio guide.
A useful question is therefore: “Which exact plan does this quoted TER belong to, and where can I check its current disclosure?” Ask for the source, not merely a number repeated in a message. Keep your comparison attached to that identifiable plan.
What exit load describes
Exit load is a different part of the discussion. AMFI’s NAV guidance explains that the redemption price includes exit load if it applies. The actual conditions need to be checked for the investment concerned; a general statement about mutual funds is not enough.
For example, a hypothetical rule might apply a charge to a particular redemption within a stated period. That illustration is not a universal rule and should not be copied into an investment decision. The relevant scheme terms and the units being redeemed determine what needs checking.
Read AMFI’s explanation of NAV and redemption price, then ask the fund house or your investment-service provider to identify the applicable terms for your transaction. Confirm the answer before submitting the redemption request.
Ask two separate questions
The first question is about holding the investment: “What ongoing expenses apply to this plan?” The second is about a proposed transaction: “Would redeeming these units on my intended date attract an exit load?” Keeping these questions separate makes the response much easier to assess.
A useful comparison sheet has distinct spaces for the exact plan, the current expense disclosure, the applicable exit conditions and the source date. Leave an entry unresolved if you cannot verify it. An empty box marked “confirm with AMC” is better than a confident number borrowed from another scheme.
Avoid turning this sheet into a ranking before understanding the products. Two investments can have different mandates, risks and purposes. The sheet helps you ask consistent questions; it does not make unlike schemes interchangeable.
A simple arithmetic example, with clear limits
Suppose, purely for illustration, a redemption value before exit load is ₹50,000 and the applicable load in that example is 1%. The arithmetic would be ₹50,000 multiplied by 1%, which equals ₹500. The amount after that illustrated load would be ₹49,500, before considering any other applicable matters.
This example teaches the calculation only. It is not an actual Bright Vision quotation, a statement about a particular scheme, a current universal rate or a forecast of what an investor will receive. Real transactions require the applicable NAV, exact terms and relevant records.
Keep illustrative arithmetic separate from transaction advice. When someone sends you an example, ask which inputs are assumptions and which have been verified for your holding. A clear distinction prevents an educational example from accidentally becoming an instruction.
Why a low-cost label is not a complete investment decision
Cost deserves attention, but a cost number cannot describe every feature of a product. Before comparing percentages, write down what you need the investment to do, when you expect to need the money and what uncertainty you can reasonably accept.
Imagine comparing two transport options without saying where you need to go. The lower ticket price may be real, yet the route may not meet your purpose. Investment comparisons also need a defined purpose before the price discussion becomes useful.
A practical conversation covers suitability, risk, liquidity needs and cost together. Be cautious about a recommendation that discusses only a small fee difference while leaving the investment's role unexplained. Ask the person presenting it to describe the reason for the choice in ordinary language.
A fictional investor case study: organise the decision first
Meena, a fictional salaried investor, wants to withdraw money for a planned household expense. She sees an online comment about an exit load and assumes that every rupee in her mutual fund account must be treated in the same way.
Before acting, she gathers the complete scheme details and transaction records. She asks the service team to explain which terms apply to the units she intends to redeem, how the proposed date affects the enquiry and what information is still required. She also asks for the answer in writing so she can review it calmly.
Separately, she checks the expense disclosure for the exact plan. She now has two organised questions instead of one vague worry about “charges.” This is an illustrative decision-making scenario, not a customer testimonial, a tax calculation or a claim that a particular action produced a financial benefit.
Keep tax and other transaction questions separate
Do not assume that understanding the expense ratio and exit load completes every part of a withdrawal review. Tax treatment and other applicable transaction details need their own assessment. The answer can depend on facts that a generic social-media explanation does not contain.
Prepare those questions separately and consult an appropriately qualified professional where needed. Share accurate records through a suitable private channel, not in public comments below an article. A public conversation should not require you to disclose account numbers or personal financial documents.
This separation also improves communication. Ask the service provider to state what their explanation covers and what requires a different professional. “Please confirm the scope of this estimate” is a useful request whenever several kinds of costs are being discussed together.
Build a one-page cost enquiry
Start the page with your question: comparing a prospective investment, reviewing an existing holding or planning a redemption. Add the exact scheme and plan, then the date on which you expect to act. These details give the recipient a usable starting point.
Under a second heading, list the information you want confirmed: current expense disclosure, applicable exit conditions, documents relied on and any further details needed from you. Keep the wording neutral. You are asking for an explanation, not asking someone to validate a decision you have already made.
At the bottom, record the response date and the person or official channel that supplied it. If circumstances change, revisit the enquiry. A good record reduces the chance that an old answer will be reused for a different transaction without review.
Questions to ask before you act
- What is the complete scheme, plan and option being discussed?
- Where is the current expense disclosure for that exact plan?
- Which exit-load terms apply to the units involved in my proposed transaction?
- What dates and records are needed to confirm that answer?
- Are the numbers shown actual transaction inputs or educational assumptions?
- What other matters fall outside this cost explanation?
- How does the investment fit the purpose and timeframe I have described?
Use these questions as a preparation tool. You do not need to become an expert in every technical term before seeking help. You do need enough clarity to recognise whether the answer relates to your actual investment and intended action.
Frequently asked questions
Are expense ratio and exit load the same charge?
No. They describe different aspects of mutual fund costs. Keep the ongoing-expense enquiry separate from the redemption-conditions enquiry, and verify both for the relevant investment.
Does a zero exit-load statement mean a fund has no costs?
It does not answer the separate expense-ratio question or every other transaction consideration. Ask what the statement covers and check the complete relevant documentation.
Can I use a number from an old screenshot?
Use it as a prompt to verify the current information, not as a substitute for verification. Match the exact plan, source and date before relying on it.
Should the lowest expense ratio determine my choice?
Cost is one part of the discussion. A decision also needs a clear investment purpose and an assessment of the relevant risks and requirements. A fee comparison alone is incomplete.
Turn a fee conversation into an informed conversation
The most useful outcome is not memorising two definitions. It is knowing which information to request, which document supports the answer and which assumptions remain unresolved.
Bright Vision Investment & Services can be contacted to discuss your mutual fund service requirements and the information needed for a cost enquiry. Bring the exact scheme and plan details and explain the decision you are considering.
Investor note: This article provides general education, not a personalised investment recommendation. Mutual fund investments are subject to market risks; read all scheme-related documents carefully. The numerical example is hypothetical.
Explore more perspectives or talk to Bright Vision about your financial goals.
Explore all insights